Flood zones and insurance sit at the heart of luxury due diligence in coastal Southwest Florida. Waterfront and coastal homes make this review especially important.
A FEMA flood zone is the starting point, not the full story. It sets the context, yet it never captures a property's complete risk profile on its own.
Smart buyers read the zone alongside elevation, construction, and insurance. This guide shows how those pieces fit together before an offer.
How Southwest Florida Flood Zones Work
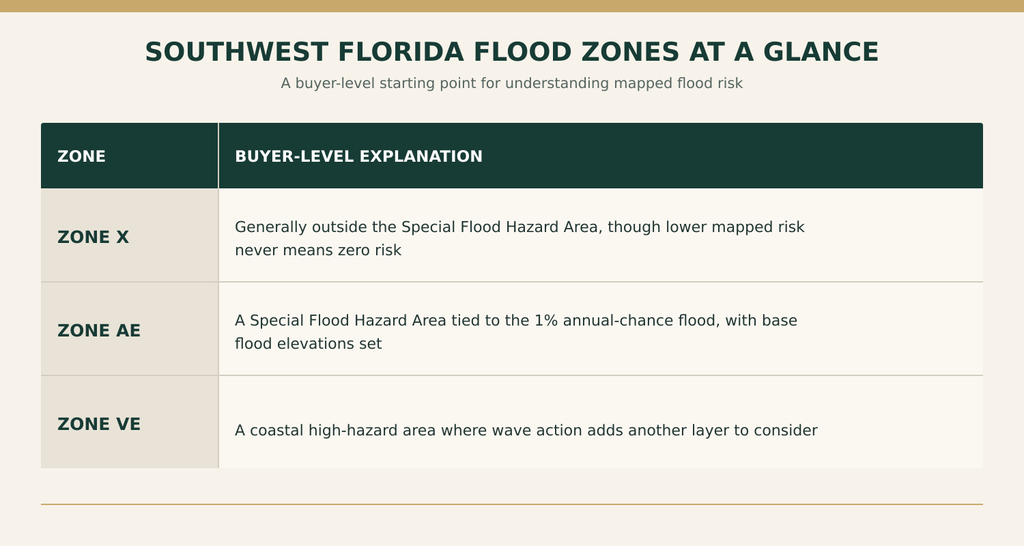
FEMA maps sort areas into flood zones based on mapped risk. A few zones appear again and again across Southwest Florida.
No single zone is simply good or bad. Always verify a property's current flood-zone designation through official sources before you rely on it.
Designations can change over time as maps get updated.
How Flood Zones Affect Insurance for Luxury Homes
Flood coverage and standard homeowners coverage are two different things. One rarely covers what the other does.
Seeing how flood coverage differs from homeowners insurance helps clarify the gap. A flood zone can shape the insurance conversation, yet it is not the only pricing factor.
High-value homes deserve a property-specific insurance review, not a generic estimate. A broad zone-based figure means little for a distinctive waterfront estate.
Lenders may also set their own coverage expectations depending on the property. Those requirements can shift based on financing and location.
Ask for property-specific insurance guidance early. Waiting until the due-diligence window tightens leaves little room to adjust.
Why Flood Zone Alone Doesn't Tell the Whole Story
The zone letter is one input among several. A fuller view weighs zone, elevation, construction, exposure, resilience, and insurance together.
A Zone X home is not automatically flood-proof. A Zone AE or VE designation does not make an exceptional coastal residence undesirable either.
Elevation and construction shape real risk as much as the map does. Buyers evaluating a high-value home should look at storm resilience and any reliable property history.
These same factors also influence how these homes hold value over time. The point is context, not a single verdict from a map.
Waterfront Luxury Requires a Different Perspective
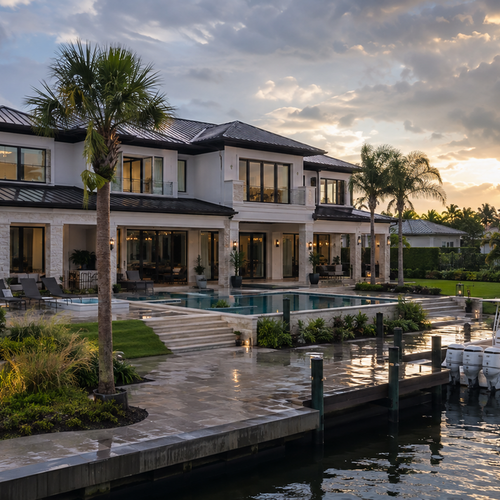
Many of the region's finest homes sit in flood zones by nature. Gulf proximity, views, and boating access come with added due diligence.
That tradeoff is part of the waterfront lifestyle, not a flaw. The goal is to see clearly what waterfront ownership involves for that specific home.
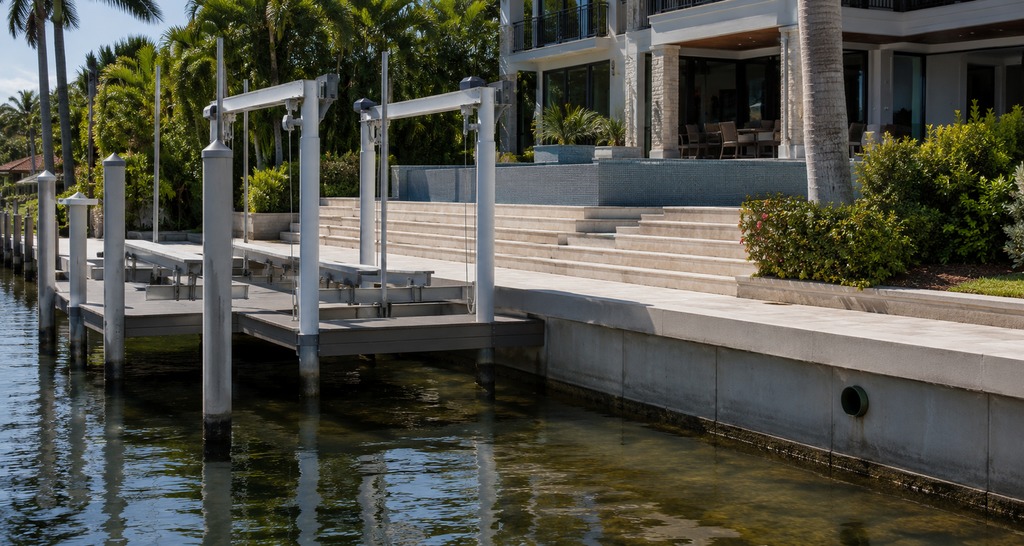
For these residences, look closely at seawalls, docks, and lower-level areas. Drainage, elevation, and storm-resilience upgrades all deserve a careful review.
The aim is never simply to avoid flood zones. It is to see clearly what comes with owning a particular luxury property.
A Luxury Buyer's Flood and Insurance Due-Diligence Checklist
A clear process turns a complex topic into confident decisions. Timing your search and due diligence gives you room to do it well.
- Verify the current FEMA flood-zone designation for the property.
- Review available elevation information for the residence.
- Ask about any known flood history and supporting documentation.
- Obtain current, property-specific insurance guidance and quotes.
- Distinguish flood coverage from standard homeowners coverage.
- Evaluate storm-resilience and construction features.
- Inspect seawalls, docks, and waterfront infrastructure where relevant.
- Review association factors, since how condo associations are evaluated matters for luxury condos.
- Consult qualified insurance, inspection, engineering, or floodplain professionals.
Working through each step protects both your investment and your peace of mind.
Making Flood Risk Part of the Luxury Buying Decision
A flood-zone designation is one important variable, not the whole decision. Weigh it against the residence, location, construction, and elevation.
Waterfront characteristics, insurance profile, and lifestyle goals all belong in the mix. The right home balances risk awareness with the life you want.
Gulf and Greens helps buyers evaluate Southwest Florida luxury real estate within this fuller context. We coordinate with the right insurance and technical professionals for specialized guidance.
Every luxury purchase deserves a clear-eyed look at flood risk. Ready to evaluate a property the right way? Speak with our team to start today.
Frequently Asked Questions
What flood zones are considered high risk in Southwest Florida?
Zones AE and VE fall within FEMA's Special Flood Hazard Area and carry higher mapped risk. VE is a coastal high-hazard zone where wave action adds concern.
What is the difference between Zone X, AE, and VE?
Zone X sits outside the Special Flood Hazard Area with lower mapped risk. Zone AE reflects the 1% annual-chance flood, and Zone VE adds coastal wave hazard.
Is Zone AE or Zone VE higher risk?
Zone VE is generally considered higher hazard. It is a coastal high-risk area where wave action, not just rising water, factors into the designation.
Does Zone X mean a Southwest Florida home cannot flood?
No. Zone X means lower mapped risk, not zero risk. Heavy rain, drainage issues, and storms can still cause flooding outside high-risk zones.
Do luxury homes in Zone AE require flood insurance?
Requirements often depend on financing and lender rules. Homes in a Special Flood Hazard Area with a federally backed mortgage typically must carry flood coverage.
Does homeowners insurance cover flooding in Florida?
Generally no. Standard homeowners policies exclude flood damage. Flood coverage is a separate policy, so buyers should review both carefully before purchasing.
How does elevation affect a luxury home's flood risk?
Elevation can significantly influence real risk and insurance considerations. A higher-elevated home may face different exposure than the flood-zone letter alone suggests.
Should buyers avoid waterfront homes in FEMA flood zones?
Not necessarily. Many premier waterfront homes sit in flood zones by nature. The goal is careful due diligence, not automatic avoidance of coastal property.
How can I check the flood zone of a Naples or Southwest Florida property?
Use FEMA's official Flood Map Service Center to search by address. Always confirm the current designation, since maps update over time.
What should I review before buying a luxury waterfront home in Southwest Florida?
Review the flood zone, elevation, insurance, seawalls, docks, drainage, and construction. Then consult qualified professionals before finalizing your decision.
Check out this article next